Digging through the archives of Mortgage Strategy has been an enlightening as well as an entertaining experience.
For instance, did you know that a young Graham Norton once hosted the MS Awards?
Or that Boy George arrived as a surprise guest at another MS Awards evening, then treated the delighted audience to a medley of his classic hits?
Or that, in the very first issue, the front cover boasted a mini-headline saying, ‘Mortgage Force evicts Nick Faldo’? Sadly, the story did not prove as dramatic as the headline suggested.
Overshadowed but undaunted
The first issue of MS landed on desks in September 2001, just days after the terrorist attack on the Twin Towers in New York.
Probably not the best time to launch a magazine, but copy for the issue had already been written and pages had gone to press — so, while the world was still in shock, MS was born.
In this special 25th anniversary issue, we look back on key events, talk to past and current editors about their experiences, and also hear from industry figures who have a long association with the title.
But this is not just a trip down memory lane. We also look at what the mortgage industry has learned over the past quarter century, and what we should expect and hope for in the coming years.
Industry figures
ROBERT SINCLAIR
A regular industry face and commentator in MS throughout the years has been Robert Sinclair.
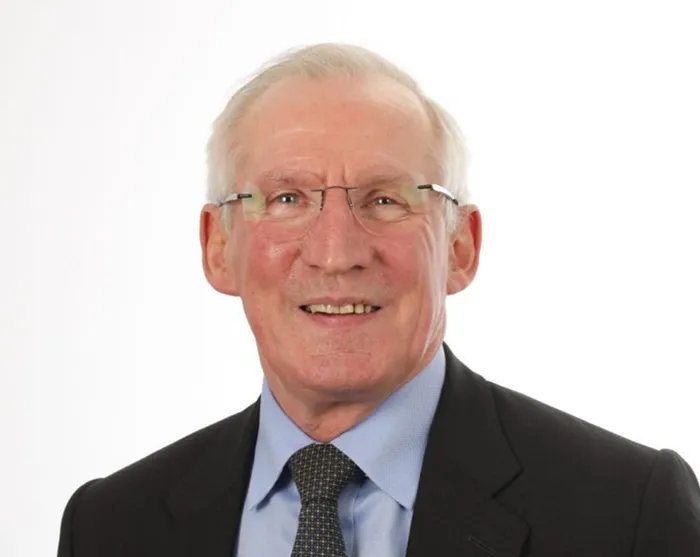
We caught up with the former chief executive of the Association of Mortgage Intermediaries (Ami) in London recently to talk about his connection with, and memories of, MS.
Back in 2001 when MS launched, Sinclair was working in mainstream banking rather than mortgages. He spent more than two decades with HSBC and later Santander UK, working across personal, private and corporate banking.
But by 2006 Sinclair had joined the Association of Independent Financial Advisers (Aifa) as a director. His role was to represent broker firms involved in consumer finance and lending. He would go on to help establish Ami as an independent organisation rather than simply a part of Aifa.
‘Forcing debate’
And it was in 2006 that Sinclair first found his name within the pages of MS — either quoted in news articles or as a bylined contributor to the magazine.
“There may have been the odd headline that I didn’t like but I can honestly say that Mortgage Strategy has brilliantly served as a mirror reflecting what is going on in the industry and forcing debate between advisers and lenders, as well as educating the broker population,” he says.
“I have been lucky to get to know a series of great journalists over the years and, with them [while head of Ami], we have been able to effectively increase awareness of core issues.”
We saw collaborative working during the pandemic and to some degree that has continued since
Since MS launched there has been no shortage of stressful events — think financial crisis, Brexit, Covid and the Liz Truss Mini-Budget. Sinclair has vivid memories of where he was on the night of the Brexit vote.
“I had been at a MAB conference and, on returning to my hotel room late in the evening after a few drinks, I briefly turned on the TV and saw people celebrating a Leave victory.
“I woke up next morning, a little the worse for wear, and thought I must have imagined the Brexit result. But I soon discovered that it wasn’t a bad dream!”
Covid-19
As a nation we are, thankfully, not used to pandemics or lockdowns. But in 2020 the UK (and much of the world) faced the biggest health threat in most people’s lifetime. Looking back, how does Sinclair think the sector coped at the time?
“I think the industry adapted incredibly well, sourcing tech and working together to keep the market going. Kate Faulkner deserves a mention here as she played an integral role in drawing all parties together.”
(Faulkner had founded the Home Buying and Selling Group [now the Home Buying and Selling Council] in 2018. It became an important cross-industry co-ordination forum during the pandemic.)
There may have been the odd headline that I didn’t like but Mortgage Strategy has brilliantly served as a mirror reflecting what is going on in the industry
Sinclair continues: “Lenders, brokers, estate agents, the media and government worked together to open up the market. We were able to pull people together and leave their commercial bias behind.
“We saw collaborative working and to some degree that has continued since. Without Covid you could argue that OPDA [Open Property Data Association] would not be where it is now.”
Sinclair adds that Covid restrictions also proved the industry could work remotely, but points out that since the pandemic there has rightly been a reassessment of the tangible benefits of working from the office; notably, a collegiate environment and a workplace that enables talent to be developed, via face-to-face mentoring.
Technology
Over its first quarter century, MS has constantly covered, written about and speculated upon the impact on the industry — both good and bad — of technology.
Sinclair accepts that the sector has benefited and can continue to benefit from tech innovation. But he warns against companies not fully understanding their artificial intelligence (AI)/tech investment, and against FOMO (fear of missing out) leading to hasty and ill-considered adoption.
“With AI, once it is bolted in it is very difficult to change. Looking forward, firms will need to take even greater care when they pick their tech provider.”
ROGER MORRIS
There is nothing subtle about the changes in the mortgage industry since 2001, according to Roger Morris, group distribution director at Chetwood Financial.
Go back 25 years and Morris was the founder and managing director of em-financial, which grew into one of the UK’s larger mortgage distributors/packagers.
“There was so much money around then,” he recalls.
“All-expenses-paid jaunts to events in Dubai. Taking press on trips to my villa in Spain for two to three days. And when you offered to take a journalist to lunch, the typical response would be, ‘It depends where you are taking me.’”
It is fair to say the premier restaurants back then were not struggling to take reservations. And gifts could be lavish and plentiful, says Morris.
There was a time, back in the early 2000s, where the industry was driven by greed. We are in a much better place today
“Back in the early 2000s, at Christmas there were Harrods hampers being delivered to offices and you’d hear people say, ‘Not another one!’”
As Morris points out, the early years of MS coincided with the huge wave of highly lucrative sub-prime mortgage business. For lending in the early 2000s there was little or no need for proof of income.
But, as we know, this boom time was not set to last. By 2007 the financial crisis was looming and advertising was starting to fall away. Interest-only mortgages essentially became a thing of the past.
With hindsight, does Morris think the industry is in better shape now, with more regulation in place?
“Without doubt,” he says. “I think there was a time, back in the early 2000s, where the industry was driven by greed. We are in a much better place today — though I would argue that there is room now to row back a little bit on regs.”
The ‘Wild West’?
Whether one can fairly describe the early 2000s in the mortgage industry as the ‘Wild West’ is debatable. What is undeniably true is that professional accreditation was at a rudimentary level compared to today.
Although CeMap examinations had been introduced in 1998, they were not mandatory. Only in December 2002 did formal mortgage adviser qualifications become part of statutory regulation. Indeed, regulation in financial services in general was only just starting to acquire a more structured appearance.
In 2001, if the Bank of England made an announcement, the industry listened
“Industry regulation and the Consumer Duty are so necessary. Go back to that period and there was nothing really in place. This lack of oversight led to things like PPI [payment protection insurance] mis-selling,” argues Morris.
“The world now is much more sustainable. After the Truss Mini-Budget, how many repossessions were there? Not many. That is because stress testing had been done.”
Promoting protection
Looking to the future, one area where Morris particularly wants to see progress is with take-up of protection by homebuyers.
In the early years of MS, interest-only mortgages were very much in vogue and this meant that life assurance was part of the deal. However, with endowments/interest-only no longer taking a large share of UK mortgage business in 2026, protection cover is too often regarded as an optional extra rather than a necessity.
Morris served for years as a volunteer in the fire service, working with teams to cut people out of vehicles after road collisions. His experiences underlined the crucial role of insurance. He witnessed firsthand how family circumstances could change both quickly and tragically. Dealing with personal loss is bad enough but, when you are also coping with massive financial pressures in the aftermath, it is even worse.
“You just can’t sugarcoat it. You need to spell out the reality of not being protected. Consider how people take for granted that buildings insurance is mandatory, but then they don’t deem it essential to insure the breadwinner! It makes no sense.”
Industry regulation and the Consumer Duty are so necessary. There was nothing really in place 25 years ago
One very significant change in recent years that Morris is keen to point out is the impact of decisions, often ill conceived, from the other side of the pond.
“Go back to 2001: if the Bank of England made an announcement, the industry listened. Currently, what we pay on our mortgage is likely to be influenced far more by what [US president] Donald Trump says!”
Just for the record, back in 2001 Trump was just that fun real-estate guy who had made a cameo in Home Alone 2!
ANDREW MONTLAKE
One of MS’s longest-standing columnists is Coreco’s Andrew Montlake, who took over the Marketwatch page in 2012 — and continues to write it today.

He explains how his association with the column came about.
“Before me, the Marketwatch page was written by Jonathan Cornell (former managing director of Hamptons Mortgages). I had stood in for him when he went on holiday.
“When he moved on to a role in the Financial Services Authority, he suggested I replace him on a permanent basis.”
Market comment
Although Montlake had been writing blogs for some time, this was his first regular column.
“Back then it seemed like it was only me and Ray Boulger writing blogs! I remember people asking, ‘Why are you wasting your time writing those things?’ But I thought it was important to comment on the market; not present a sales pitch but tell things as they were.”
Today, a single social-media post from the Oval Office and rates here can jump
Montlake also stresses that blogs were a good way of getting around compliance because they were just personal opinions. At one point he was writing a blog every working day, and competition from other sources was pretty thin on the ground.
“It is very different now as so many people in the industry produce blogs.”
As for Marketwatch, Montlake’s content has evolved.
“To start with it was more about highlighting products that were coming to market and rates on offer. But, when the magazine moved from a weekly to a monthly, the copy was more time sensitive, so it became far more opinion and analysis.”
Global impact
He agrees with Morris that the UK market is far more impacted by global events than it was in the early 2000s.
“The credit crunch was the start of it — something happening overseas that can fundamentally affect the UK too. Since then, the world has just got smaller and smaller.”
He adds: “Now, a single social-media post from the Oval Office and rates here can jump.”
However, some wounds to the UK economy, and subsequently to interest rates, have been undeniably self-inflicted.
We may moan a fair bit on the way, but we face challenges head on and come out the other side stronger
“The sheer stupidity and arrogance of the Liz Truss Mini-Budget were breathtaking. I don’t think we have fully recovered.”
Whether industry challenges over the years have been due to madcap budgets, wars, tariffs, energy prices, referenda, or housing or banking crises, the sector itself has proved resolute.
As Montlake concludes: “You are a product of all your experiences, and this industry, now regulated in the right way and far more diverse, has matured. It has an entrepreneurial spirit.
“We may moan a fair bit on the way, but we face challenges head on and come out the other side stronger.”
MARIA HARRIS and LIZ SYMS
Long-time contributors to MS, Maria Harris, chair of OPDA, and Liz Syms, chief executive and founder of Connect Mortgages, discuss how far the industry has come since the launch of the magazine in 2001.

Syms describes the amount of change over the past 25 years as “enormous”.
She explains: “When Mortgage Strategy launched in 2001, mortgage advice sat largely outside statutory regulation. Self-certification and 100%-plus lending were commonplace, and a great deal of business was still done on paper and over the phone.”
Since then, the market has lived through the arrival of statutory regulation in 2004, the credit crunch and the collapse of Northern Rock, the near-disappearance of specialist and higher loan-to-value lending, and then a long rebuild.
The next chapter for women is less about access and more about progression
Syms also notes the industry has absorbed the Mortgage Market Review, the move to the Financial Conduct Authority, the Mortgage Credit Directive and, most recently, the Consumer Duty. In her opinion, regulation has been “the single biggest shaping force of the past 25 years, and on balance a positive one”.
She adds: “It has professionalised the sector, driven out some of the poor practice that existed before 2004, and given customers real protection they did not previously have.”
‘Far more resilient’
Alongside all of that, Syms highlights that the industry has weathered a pandemic and the rate shock that followed the 2022 Mini-Budget.
She says: “The mortgage market has overcome each of these by becoming more professional, better capitalised and far more resilient.
“What strikes me most is that brokers came through every one of those challenges with their share of the market growing, not shrinking. That tells you how much borrowers value good advice when things are complicated.”
Meanwhile, Harris says when she joined the industry in November 2005 it was a “culture shock”.
Harris started in the mortgage market after a decade working in travel followed by utility contact centre management.
Her first role was covering the Halifax Intermediary Service Centre in Glasgow, where the teams worked through mortgage applications contained in manilla folders, every document was stamped and certified by the broker, and they had a whiteboard to track fund release dates and completions.
I’d love to see more talent and progression schemes, and I encourage all my male peers to become an advocate for someone who is up and coming
She says: “It felt like I’d stepped back in time. It was a difficult first few years as we navigated the financial crisis and saw HBoS transition to Lloyds with the loss of much-loved brands and breaking up whole teams. What never changed was the people and the depth of industry relationships. I’m still good friends with many of those I met in my first year in the industry.
“It’s been great to see the industry evolve since then with the launch of neo banks and lots of new customer propositions, including specialist lending, product transfers and the move to digital solutions such as Open Banking.”
Role of women
Syms and Harris agree that the industry has come a long way in terms of recruiting and developing roles for women. When Syms started out in the market, rooms were almost entirely male.
She recalls: “I remember being asked by more than one male colleague, ‘Where do we get tea and coffee?’”
Syms continues: “As a woman founder of a business I was definitely in the minority, but that is no longer the case. Today women are visibly leading networks, lenders, clubs and trade bodies; we have industry award categories and leadership lists that celebrate them; and initiatives such as the Women in Finance Charter have held firms accountable for real, measurable change rather than good intentions.
“Progress is good, but not finished.
I see the adviser’s role broadening beyond the mainstream mortgage, so we look after clients across their whole life
“Even though there are far more women in leadership positions, I believe there are far fewer women founders of businesses. The next chapter is less about access to the industry and more about progression.”
Also looking back, Harris remembers attending her first event in the mortgage market in 2006 and wondering where all the women were.
She says: “It wasn’t something I’d noticed as much in the office or out in the field as there were lots of female mortgage administrators and brokers, but that wasn’t reflected at senior management level.”
There has been a lot of focus on diversity and inclusion over the past 25 years.
Harris says: “You can see the difference in how the industry is represented at events, in the press and around the leadership table, but we’re not there yet.”
She would “love to see more talent and progression schemes, and I encourage all my male peers to become an advocate for someone up and coming.
“The mentorship and support I have had throughout my career have made a huge difference”.
‘Exciting transition period’
Events of the past quarter century have tested every inch of the mortgage market’s resilience, but Harris believes the industry is about to enter “one of the most interesting and exciting transition periods” since she joined in 2005.
It’s been great to see the industry evolve, with the launch of neo banks and lots of new customer propositions
“The next generation of digital transformation, the launch of smart data schemes and the recent government announcements to improve the homebuying process will fundamentally change the customer and broker journey,” she says.
“Brokers will have access to data and digitised solutions in a way that they’ve never had, and the introduction of digital property packs will be mandated by 2029, so there’s not long for everyone to be smart data and trust framework ready!”
Trust in advisers
Meanwhile, Syms is optimistic about the continuing importance of the adviser role.
She says every prediction that technology would replace the adviser has been proved wrong, because “the more complex the market becomes, the more people value someone they can trust who can guide them through it”.
The past few years of rate volatility, tighter affordability and a growing population of borrowers who do not fit the standard profile have all pushed more business towards advice.
Brokers came through every challenge with their market share growing, not shrinking. That tells you how much borrowers value good advice when things are complicated
Syms explains: “I expect advisers to become even more central, but successful ones will embrace technology to handle routine tasks so they can spend their time cultivating relationships and providing guidance only a human can give.
“I also see the adviser’s role broadening beyond the mainstream mortgage, so we look after clients across their whole life. The firms that invest in their people, their technology and their professionalism have a very bright future.”
The editors
ROBYN HALL (Launch editor, September 2001-09)
ROBERT THICKETT (2009-14)
Days before the press deadline for the first issue of MS, the editorial staff were sent home at lunchtime with the news pages still bare.
It was 11 September 2001 and the recently hired team had watched the TV news as the second hijacked aircraft hit the World Trade Center in New York.
Founding editor Robyn Hall and reporters Helen McCormick and Ben Stafford returned to the MS office the next morning, but none of their industry contacts were answering the phone.
“Nobody wanted to talk about mortgages,” Hall recalls.
But the team ultimately filled their pages and hit the press deadline. The magazine launched on 17 September.
Many brokers were questioning whether they could make a living from mortgages
Hall had joined Centaur (the publisher) earlier that summer from monthly title Mortgage Introducer to launch the industry’s first weekly magazine for brokers. It was born out of the increase in intermediary lenders with a growing appetite for business and advertising budgets to match.
Hall recalls Centaur knocking down a stationery cupboard and shuffling desks around to carve out a corner of the office for MS staff.
No lack of news
Soon there was no shortage of news stories. Proposals for statutory mortgage regulation were extended to cover advisers, and the new magazine would play a central role in helping the industry navigate the transition.
MS followed that journey from industry self-regulation to what became known as ‘M-Day’ (Mortgage Day), on 31 October 2004. Hall was there, in a central London office at 44 minutes past midnight, when the first regulated mortgage offer was issued, to a couple called John and Linda Philpin.
Also present were Alan Cleary from BM Solutions, which provided the mortgage, and John Charcol’s Ray Boulger. It was a strange way to spend a Sunday night, Hall recalls.
“There weren’t any fireworks, but it was an historic moment.”
Suddenly, this niche financial subject was front-page news
MS’s Mortgage Mole page provided some light relief as brokers’ regulatory burden increased. Inspired by similar columns in the Evening Standard and Private Eye, the diary section was created because Hall and his reporters were out most weekday nights at industry socials.
Much of the gossip they picked up could never be attributed in a news story, so it found its way into Mole, which became a major talking point.
“People would read the magazine from back to front, first checking to see who had been up to what in Mole before they turned to the serious news,” says Hall.
As lending boomed, so did MS, with editions running to more than 100 pages and broker summits held in Jerez and Dubai.
However, fierce industry competition resulted in escalating levels of risk in the years following M-Day. Northern Rock’s now notorious Together mortgage took lending up to 125% LTV and Alliance & Leicester had a similar deal. Lenders allowed borrowers to self-certify their income and sub-prime criteria became ever more permissive.
MS covered product launches by lenders allowing “unlimited county court judgments” and as many as four missed mortgage payments in the previous year.
The crash
In September 2007, everything changed. Robert Thickett, then MS news editor, remembers hearing whispers of trouble at Northern Rock, before Robert Peston’s announcement on the BBC evening news that the bank needed emergency funding.
The next day, customers queued around the block at Northern Rock branches to try and withdraw their savings in the first run on a British bank since 1866.
“Suddenly, this niche financial subject was front-page news and everyone wanted to know about sub-prime mortgages and securitisation,” says Thickett.
“It was shocking to see how quickly the market unravelled and we didn’t know which lender would be next.”
The Funding for Lending Scheme acted like a course of steroids for the mortgage market
A year later came the collapse of Lehman Brothers, followed by government rescue packages for HBOS and Royal Bank of Scotland.
Thickett, who had joined MS in 2003 as a reporter, became editor in 2009 when the market was still reeling. That year the Bank of England cut Bank rate to a record-low 0.5% and launched ‘quantitative easing’ (QE) in a bid to stimulate the economy.
But the market continued to shrink until 2010, when the Council of Mortgage Lenders recorded gross lending of only £134bn — less than half the £364bn posted at the 2007 peak.
“You could see the damage across the intermediary sector,” says Thickett. “Networks were going under or merging, there was a bloodbath of packagers, and many brokers were questioning whether they could make a living from mortgages at all.”
The adviser market was “decimated”, according to one MS article of the time, which reported that the total number of brokers had shrunk from 36,000 in 2007 to an estimated 12,000 in 2010.
People would read MS from back to front, first checking to see who had been up to what in Mole before they turned to the serious news
“Dual pricing was a huge problem as lenders tried to entice borrowers to deal with them directly by offering lower rates. Brokers felt betrayed as they had helped lenders to build up business in the good years and now they were being squeezed out,” explains Thickett.
It was a testing time for MS too, as lenders slashed the advertising budgets it relied on. But the printing press kept rolling every week against a turbulent financial and political backdrop.
Coalition government
In May 2010, prime minister Gordon Brown and his chancellor, Alistair Darling, left Downing Street, replaced at numbers 10 and 11 by David Cameron and George Osborne. In the early years of the Conservative-Liberal Democrat coalition government, the market stuttered along at low levels.
Then, in July 2012, just weeks before the opening ceremony for the London Olympics, the Funding for Lending Scheme (FLS) was launched to give banks and building societies access to cheaper funding.
It acted “like a course of steroids for the UK’s mortgage market”, Thickett wrote in his MS Leader column. Help to Buy followed in 2013 to boost access to higher-LTV lending.
Yet the scale of intervention raised questions about how sustainable the recovery really was. Thickett compared the housing market to Frankenstein’s monster, “artificially kept alive” by record-low interest rates, QE, FLS and Help to Buy.
On M-Day in 2004, there weren’t any fireworks but it was an historic moment
By the end of Thickett’s tenure, the regulatory response to the crash was also reaching its conclusion. In April 2014 the Mortgage Market Review (MMR) rules came into force. By then, self-certification had disappeared and lenders had already clamped down on the excesses of the sub-prime boom, but the MMR was designed to prevent a return to those extremes.
Borrowers now faced forensic questions about their spending habits, including how much they spent on wine and whether they bought steak when friends came round for dinner.
The new rules effectively made advice mandatory for the majority of mortgage sales, putting intermediaries at the forefront of the industry once again.
Thickett says: “I left MS as the MMR came in and the era of the broker began. This saw the share of all mortgages arranged by brokers soar from a low of 50% to around 90% today.”
PAUL THOMAS (2014-16)
At the helm of MS for two years from 2014, Paul Thomas casts his mind back over a decade.
“I joined [MS sister title] Money Marketing in 2010 as the mortgage reporter. I was the black sheep of the family on an IFA-focused title.
“MS was the magazine you really wanted to be on. The opportunity came up, I joined in 2012 as deputy editor and it was up there with some of the best times of my career.
“You’re on a mag that is highly respected, encouraged to get good stories, backed to the hilt. I was under Rob Thickett, who was an excellent editor.
“Everyone saw Strategy as the title to beat when it came to getting news. It was highly competitive, we were all in our 20s and keen to outdo each other, and it was fantastic for readers.”
As for the market itself, Thomas entered just in the wake of the financial crisis.
The thing I’m most proud of is how fiercely Mortgage Strategy championed the broker
“It was only when I became editor that the market started picking up; not that I’m taking responsibility for it!” jokes Thomas.
The MMR in 2014 was a big change for the industry, and for MS. The title went through a major redesign and Thomas picked the purple logo, which he found out later was highly divisive!
Corporate hospitality
“I definitely think being a reporter on a trade mag back then was a single person’s game,” he says.
“I spent more time with people from the market than I did with family and friends. I spent four, five days a week out sometimes, and weekends.”
The press jolly that sticks out for Thomas is the Precise bus trip to the Six Nations rugby at Twickenham.
“They would start in Mayfair, have a few drinks, and we’d get taxis down to this double-decker bus parked near the Harlequins stadium. It acted as a little base, and the drink of the day was a Black Velvet — Guinness and champagne — which flowed freely. Needless to say it was a long old day, drinking-wise.
You’re on a mag that is highly respected, encouraged to get good stories, backed to the hilt
“I saw all sorts of games; Ireland, England and a couple of times I got to see Wales. Rugby was a big tick, being a Welshman. Great company and amazing opportunities to meet people in the industry that you didn’t necessarily otherwise get to mix with.”
MS was a weekly back in 2014, so a very different schedule from today. It may have been more hectic, but Thomas loved it.
“I never saw myself as a features writer. I was all about getting the news in, getting it out, move on to the next one. I love the weekly cycle and working at that pace.
“But it did have its drawbacks. If the advertising team said we had to go up by a couple of pages, it could be a challenge to fill them within a two-hour deadline!”
Press day
Thomas recalls how a typical press day would play out.
“You would get into the office, scan the newspapers for mortgage stories and see whether we needed to follow something up. I’m proud to say that, on MS, that was quite rare. We were always in or around the leaders in getting the stories out.
“Next, everything seems a little relaxed for an hour or so, then you realise you’re awash in big A3 bits of papers with a blown-up version of the news pages, ready to be checked over.”
After which, Thomas explains, it’s a bit of a blur.
Being a reporter on a trade mag in 2014 was a single person’s game. I spent more time with people from the market than I did with family and friends
“Every i and the cross on every t has to be accounted for. When you have reporters, you have to trust them; you’re acting as a safety net to double check. But as editor you’re ultimately responsible for what goes out each week.
“We had some brilliant reporters over the years. The design team deserve huge credit too.”
Perhaps surprisingly for a weekly title, press day back then was Friday. It may not have been universally popular but it had its upside.
Thomas elaborates: “On a Friday, the first thing you’d do after sending the mag off would be to go across the road for a drink at the Adam and Eve or the Champion pub, and you really felt you’d earned it. Friday felt like FA Cup Final day for 52 weeks a year.”
The biggest stories
Which stories that MS covered stand out from that era?
“When it came to the biggest stories, there was a very good chance you’d read about them in Mortgage Strategy first, whether it was breaking the Help to Buy mortgage guarantee scheme or HSBC’s entry into the broker market,” says Thomas.
“But more than anything, the thing I’m most proud of is how fiercely we championed the broker. That spirit ran through everything we did — and I’m glad to see that continues to this day.”
Everyone saw Strategy as the title to beat when it came to getting news. It was highly competitive and it was fantastic for readers
During Thomas’s time on the mag, MS campaigned, long and hard, on a variety of issues, from proc fees to panel removals. And, wherever it saw injustices, it shone a light on them.
“I may be biased but I felt our coverage of the Mortgage Market Review and its ramifications, for both brokers and their clients, was unrivalled at the time.”
Thomas concludes: “Whenever brokers needed an ally, we were in their corner, reporting without fear and never for one moment forgetting who we were writing for.
“If brokers from that time remember us as the title that always had their back, I’ll be a happy man.”
REBEKAH COMMANE (2016 to present)
The current editor of MS, Rebekah Commane, took over the reins back in 2016, which makes her the longest-serving editor. She reflects on her time in the hot seat.
“I had written for MNM from 2012 to 2015, so I knew the industry and the people in it pretty well,” says Commane.
“I had gone freelance and was predominantly a travel writer but it wasn’t really what I wanted.
“When the editor role at MS came up, I had initial reservations about leaving the freelance world. But I remembered how welcoming people were in the mortgage sector and I still had good contacts. That swayed it.”
Industry camaraderie
In 2016, MS was a weekly with only one other full-time staff member.
To say the workload was intense is an understatement. But, as a time to work in the industry, Commane looks back fondly.
“When I took on the role in September 2016, the market was still reverberating from Brexit. But the base-rate cut meant mortgage prices were at record lows and activity was picking up after the initial shock.
“Even in the hardest times, though, there has always been a sense of camaraderie and determination to maintain positivity in the market. That’s what has kept me and so many others in the industry.
I’m proud that we have survived some of the harder years, and that we’ve persevered with the print magazine, while also adapting to a more digital presence
“Casting my mind back, one of the major concerns [a topic that MS covered in detail] was the threat of ‘robo-advice’: a genuine worry that brokers could fall by the wayside. It was the start of the fear that people would just use a computer for guidance.”
The advance of tech will always be both a challenge and an opportunity for brokers, but that initial fear of ‘robo-advice’ taking over has abated. And this is supported by the fact that, currently, for UK residential mortgage originations, roughly 75%–80% are arranged through intermediaries/brokers.
Weekly to monthly
In 2017, MS changed from a weekly to a monthly magazine.
“I pushed against it at first,” Commane recollects. “I knew how much readers valued the paper product.
“But we made sure the monthly had much more coverage. We introduced new pages and more features and industry analysis. I remember we had a launch party and the transition went well.”
When I took on the role in September 2016, the market was reverberating from Brexit
Producing magazines in the middle of a pandemic was not something journalists had ever had to deal with, but in 2020 that changed — and it meant doing things very differently.
“I had just returned from maternity leave, working two days a week in the office,” says Commane. “Within three weeks, lockdown was introduced and I was back at home, with no nursery or childcare!
“The MS Awards were scheduled for the end of March and we were all ready to go but had to cancel at the last minute.”
Circumstances meant that the printed version of MS had to be paused for a while. The emphasis was on how best to use technology to communicate across and within the industry.
“We set up a host of virtual roundtables and webinars, and in 2021 the MS Awards were held ‘online’,” says Commane.
I remembered how welcoming people were in the mortgage sector and I still had good contacts. That swayed it
“It worked out really well. Everyone filmed themselves drinking champagne, and the compere, [comedienne and actress] Sally Phillips, was in a studio.”
Mortgage community
It is over five years since lockdown, and production schedules returned to normal.
Commane believes MS (and its daily online news service) is in good shape to inform, enlighten and connect not just today’s mortgage advisers but the next crop.
“As a brand, I’m proud that we have survived some of the harder years — especially Covid times when many other media brands folded — and that we’ve persevered with the print magazine, while also adapting to a more digital presence.
 “We couldn’t do it without our readers and the whole mortgage community. We’re in it together!”
Blast from the past: 10-year birthday issue, September 2011
Back in 2011, Mortgage Strategy celebrated its 10th anniversary. Its publishing director, Patrick Ponsford, explained the rationale behind the launch a decade earlier, and how the magazine had fared since.
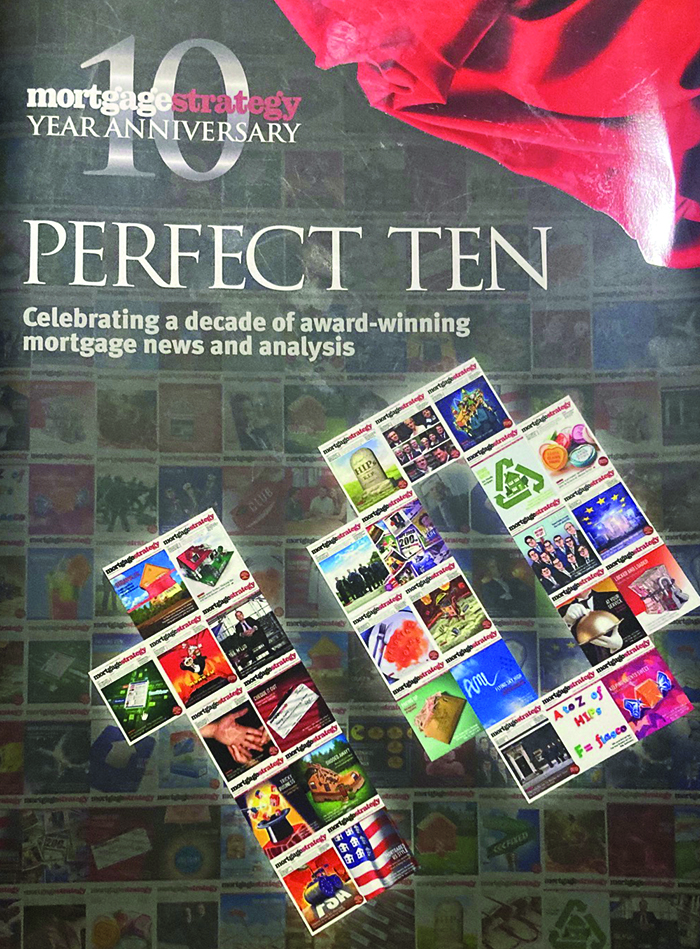 Ponsford was asked: who had the original idea to launch Mortgage Strategy?
“This is a controversial one…. Lots of people have tried to take credit for the launch of Mortgage Strategy, but the truth is the industry was just ready for its own specialist weekly publication.
“Back in 2001, we looked at the quality of journalism in the mortgage monthly titles that were around at the time, and it was not great. We believed we could do a lot better.
The industry was just ready for its own specialist weekly publication
“So we put together a publication that was more user friendly, detailed and useful, and that continues to be the case to this day.
“Sadly, that can’t be said for our rivals as, 10 years on, those monthly magazines are still appalling. “As the saying goes: plus ça change.”
Now say what you really mean, Patrick!
This article featured in the September 2026 edition of Mortgage Strategy.
If you would like to subscribe to the monthly print or digital magazine, please click here.